Foreclosure rates are Creeping Upward! Team Thayer #realestate #housing #housingmarket #news #oregoneugene #oregon
 December painted a different picture for consumer credit default than November, with most indices either holding steady or doing an about face from the previous month, according to the S&P Dow Jones Indices and S&P/Experian Consumer Credit Default Indices for December 2015 released Tuesday.
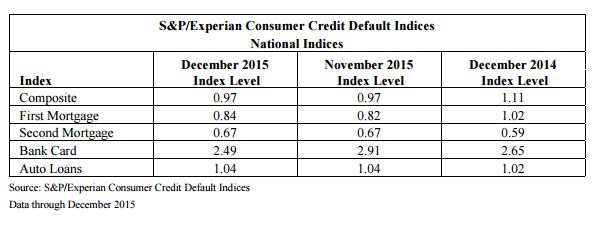
The composite index remained unchanged from November to December at 0.97 percent; however, the first mortgage default index—one of four indices that make up the composite—ticked up by two basis points from 0.82 percent up to 0.84 percent. December marked the third consecutive month with an increase for the first mortgage default rate, which climbed by one basis point in November and five basis points in October.
Even after the three straight months of increases, December’s first mortgage default rate was still down by 18 basis points from December 2014’s rate of 1.02 percent. The second mortgage default rate held steady in December at 0.67 percent after spiking by a total of 20 basis points over the previous two months. December 2015's second mortgage default rate of 0.67 percent is up by eight basis points year-over-year.
For the remaining two indices that make up the composite rate, the default rate on auto loans was unchanged over-the-month in December at 1.04 percent while the bank card default rate plummeted by 42 basis points down to 2.49 percent.
"The first mortgage move was not unusual given past patterns,” said David M. Blitzer, Managing Director & Chairman of the Index Committee at S&P Dow Jones Indices. “There were no seasonal patterns or other concerns that stand out."
Blitzer continued, “The consumer economy looks good. Consumer credit default rates are low and stable, and consumer sentiment measures are upbeat. Personal consumption expenditures rose 2 percent in 2015 (December to December) with spending on durable goods up 4.8 percent for the same period. Auto sales continued strong at the end of last year. Real disposable personal income rose 3.7 percent in the year to the third quarter of 2015. There was no response among consumers to the Fed’s recent rate increase, no rush to apply for mortgages.”
Three of the five major cities experienced a decline in their default rates from November to December. The rate in Los Angeles was down by 9 basis points (to 0.65 percent), Chicago’s default rate was down by three basis points (to 1.00 percent), and the default rate dropped by four basis points in Miami (to 1.44 percent). The two cities that saw increases were New York (nine basis points up to 1.04 percent) and Dallas (up 22 basis points to 1.10 percent).
“While the economic news on Main Street is good, the New Year opened with turmoil on Wall Street as stock prices dropped in the opening week and the market crossed the 10 percent correction mark in the second week,” Blitzer said. “The two factors being cited for weakness on Wall Street are the strong dollar and weak oil prices. For consumers, both of these are good stories—cheap gas and lower prices on imports. Other parts of the economy also favor consumer spending: the unemployment rate is down to 5 percent and the weekly initial unemployment claims reports signal further economic growth. Inflation remains low, lower than the Federal Reserve would like. Consumers aren’t showing any signs of anxiety driven by the stock market.”
 |
| Justin Lee Thayer 541 543 7287 |