When distressed properties account for a large share of all residential home sales, it tends to pull down the prices of non-distressed homes, since foreclosed and REO properties typically sell at a discount to non-distressed homes.
Yet even though the distressed sales share remains high, home prices are not slowing. According to CoreLogic’s latest Home Price Index, prices appreciated at 6.8 percent year-over-year in October. A recent report from Zillow indicated that a lack of affordability in the housing market in urban areas may drive would-be homebuyers out to the suburbs.
Since why is the high volume of distressed properties selling at discounted prices pulling down the prices of non-distressed homes, as is usually the case?
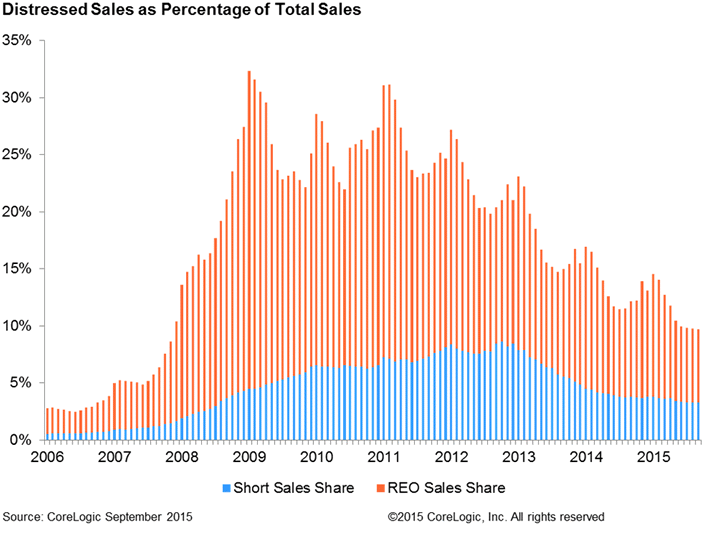
“The number and share of distressed sales have fallen between September 2014 and September 2015,” CoreLogic Chief Economist Frank Nothaft said. “The distressed sales share in the most recent month was 9.7 percent, compared with 12.1 percent in September 2014. Thus, while distressed sales often do sell at a discount, there are fewer of them in the latest month compared with a year ago, so the potential negative effect on home prices has lessened over time.
 “Overall, the homes-for-sale inventory remains relatively lean, while demand to buy homes has increased because of an improving labor market, more optimistic levels of consumer confidence, and continuing low mortgage rates. Increased demand in the face of lean for-sale inventory has prompted further value appreciation for non-distressed homes.”
Though the distressed sales share remained at nearly five times its pre-crisis level, the share of REO sales is down. In September, REO properties accounted for 6.4 percent of all residential home sales, the lowest level since October 2007 when it was 6.2 percent. At their peak in January 2009, REO sales accounted for 27.9 percent of all home sales. Meanwhile, in September 2015, short sales made up 3.3 percent of all residential home sales. The short sales share has been in the 3 to 4 percent range since dropping below 4 percent in mid-2014.
The five states with the highest distressed sales share in September 2015 were Maryland (20.7 percent), Florida (19.6 percent), Michigan (19.6 percent), Connecticut (19.1 percent), and Illinois (18.2 percent). All but eight states had lower distressed sales shares in September 2015 compared with September 2014, but only North Dakota and the District of Columbia were down to within one percentage point of their pre-crisis levels.